The Brochure Number Is Designed To Stop You Calculating#
Every business school leads with the same figure: the average package. It is prominent, it is large, and it is almost useless for the decision you are making.
It is useless for three reasons. It is an average, so a handful of exceptional international offers pull it upwards past anything a typical graduate will see. It is cost to company, so it bundles a joining bonus, a relocation allowance, stock valued at today's price and provident fund contributions, none of which arrive in your bank account monthly. And it says nothing whatsoever about what the degree cost you, which is the other half of every return calculation.
Meanwhile the numbers that actually determine whether an MBA improves your life are never on the hoarding. They are four figures you can compute in about twenty minutes with a calculator, and once you have them the ranking you started with frequently rearranges itself.
This article is that calculation. It is a companion to a straight institution-by-institution comparison rather than a substitute for one: work out these four numbers first, then compare schools within whatever range they permit.
Background: The Terms You Need To Get Right#
Four definitions, because getting these wrong is what makes the arithmetic fail.
Total cost. Not the tuition fee. The tuition fee, plus accommodation and living expenses for the full programme duration, plus examination and material costs, plus the salary you forgo while studying. For most candidates the forgone salary is the largest single component and it appears in no prospectus.
Median package. The middle figure when every placed graduate's offer is lined up in order. Half the cohort earned more, half less. This describes a typical outcome in a way the average does not. Ask for it by function if you can, since the median for finance and the median for general management within one school can differ substantially.
Take-home pay. What reaches your bank account monthly after tax and deductions. A twenty lakh cost-to-company package does not produce a twenty lakh annual cash flow. Working with cost to company throughout the calculation will give you a flattering and wrong answer.
Payback period. The number of years until your cumulative additional earnings after the MBA exceed your total cost. This is the single most useful number in the entire decision, and almost nobody computes it.
Number One: Your Total Cost#
Add these, honestly.
Programme fee for the full duration. Not the first year. Ask what the fee was three years ago at the same school and compute the actual rate of increase rather than accepting a stated percentage.
Accommodation, food and living expenses across the whole programme. Metropolitan campuses cost more than others and the difference over two years is material.
Travel home, materials, laptop, and the various incidental costs that arrive unannounced.
Forgone salary. Your current annual take-home pay multiplied by the programme duration in years. If you are entering directly from undergraduate study with no job, this is lower but not zero, since you could have been earning something.
For a candidate earning twelve lakh a year entering a two-year programme with a twenty-seven lakh fee, the total lands somewhere around fifty-five to sixty lakh once living costs are included. That is the number to work with. Not twenty-seven.
Number Two: Your Realistic Outcome#
This is where optimism does the most damage.
Use the median, not the average. If a school will not provide one, ask why. Reluctance here is informative.
Use the median for your intended function, not the institute-wide figure. A school's overall median may be pulled by a strong consulting cohort that you have no realistic prospect of joining if you are targeting operations.
Use the median for people with your background. The better schools track outcomes by prior industry and function. Ask what happened to candidates who came in from where you are coming from. That number predicts your outcome far better than any aggregate.
Convert to take-home. Estimate the cash that actually reaches you monthly after tax. This is typically substantially less than the cost-to-company headline.
And subtract what you were already earning. The MBA's return is the increase, not the total. A candidate going from twelve lakh to twenty-four lakh has gained twelve lakh a year, not twenty-four. This distinction is skipped constantly and it doubles every return calculation that skips it.
Number Three: Your Loan Burden#
This is the number that should carry the most weight and usually carries the least.
Compute the monthly instalment on the loan you would actually need, at current education loan rates, over a realistic tenure. Most banks publish calculators.
Express it as a percentage of expected monthly take-home pay.
Then interpret it honestly. A repayment consuming a modest share of take-home leaves you with choices. One consuming a large share means that for several years you must maximise salary, which is precisely the opposite of what an MBA is supposed to give you. You cannot take the interesting role at a smaller organisation. You cannot start something. You cannot move sideways into a function you find more meaningful. You are locked into the highest bidder.
This is the hidden cost of an expensive programme, and it is why a graduate of a cheaper school with a slightly lower package can end up with materially more freedom than a graduate of a more prestigious one. The degree that was supposed to open options closed them, in a way that no ranking table captures.
Number Four: Payback Period#
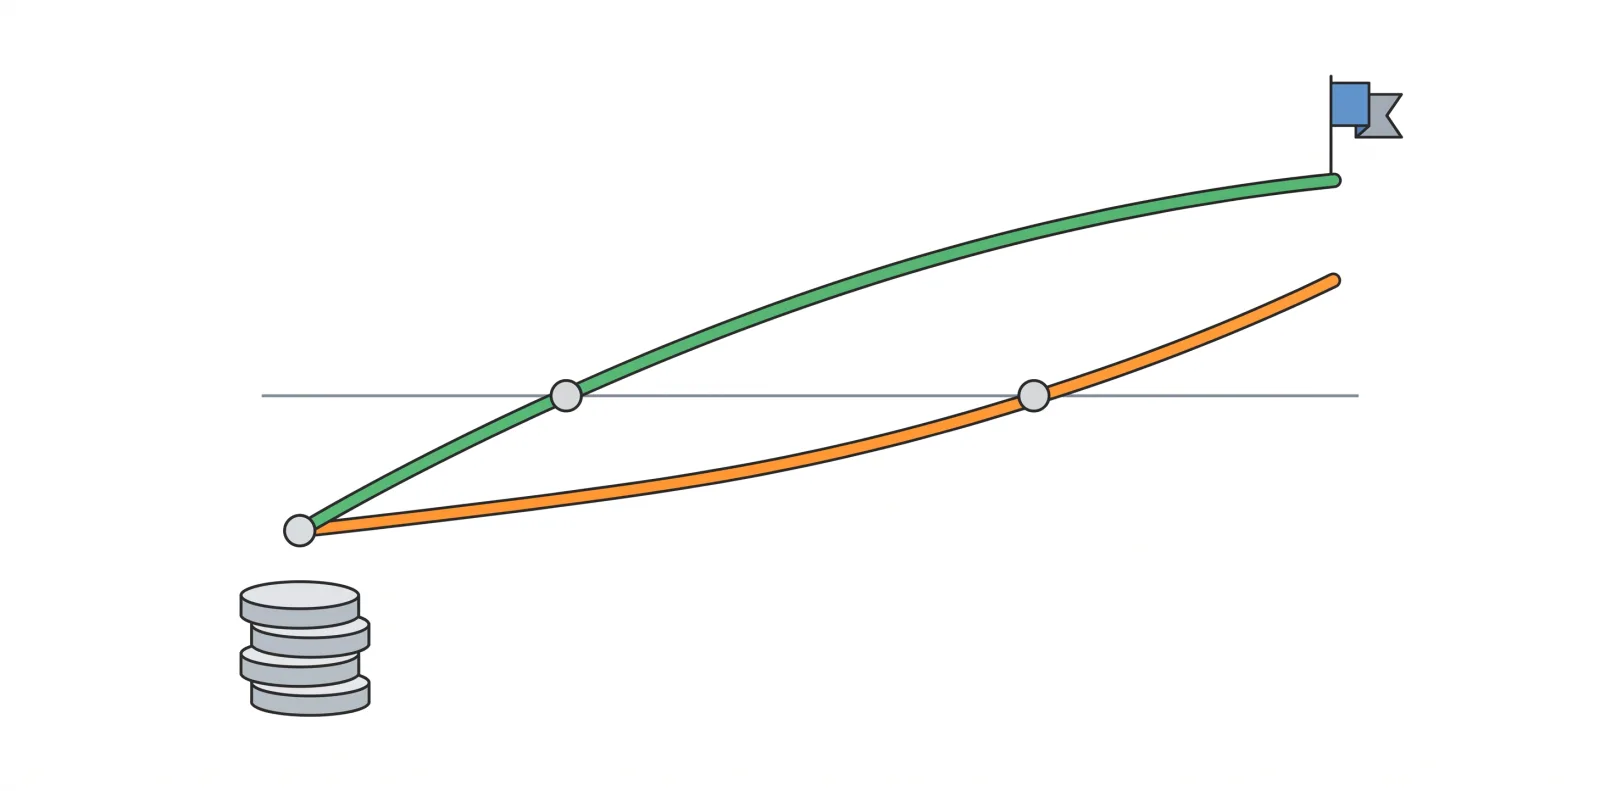
Read the crossing points, not the end points.
The red line eventually rises higher, because the larger salary increase compounds. But it crosses break-even later, and those extra eighteen months matter enormously in practice. During that period the higher-fee graduate is servicing a larger loan and has less freedom, while the lower-fee graduate has already cleared their cost and can make choices.
Which line is better depends entirely on your circumstances, and both answers are defensible.
The red line wins if you are confident of achieving the higher outcome, you can service the loan comfortably through the early years, and you intend to stay on a salary-maximising track long enough for the compounding to pay off.
The green line wins if you value early freedom, if the higher outcome is uncertain for your profile, if your family cannot absorb the larger loan without strain, or if you might want to do something unconventional in your late twenties.
And note what the chart cannot show. Career paths are not straight lines. People change function, take sabbaticals, start businesses, have children, move cities. A shorter payback survives all of those disruptions. A long one assumes seven uninterrupted years of upward salary progression, which is a strong assumption.
What These Four Numbers Change About Your Ranking#
Run them and three things usually happen.
Low-fee public institutions rise sharply. A programme charging a small fraction of its peers while producing comparable outcomes dominates on every one of these four measures. Candidates consistently underweight these schools because the fee feels like a proxy for quality. It is not.
Expensive programmes with moderate outcomes fall out entirely. There is a band of mid-market private colleges charging near-premium fees for median outcomes that do not justify them. These programmes survive on brand marketing and on candidates who never ran the arithmetic.
The gap between adjacent schools narrows. Once you are comparing on payback rather than on reputation, the difference between the school ranked eighth and the one ranked twelfth often turns out to be negligible, and your decision can be made on things that actually affect your two years: specialisation depth, location, cohort, and faculty in your area.
One honest caveat. This framework measures financial return, and an MBA is not only a financial instrument. The network, the two years out of a career rut, the exposure to people from different backgrounds, the confidence of having been tested in a serious cohort, these are real and they do not appear in any calculation. If a programme is affordable and you want it for those reasons, that is a legitimate decision.
What the framework prevents is the specific harm of committing to a large, life-shaping debt on the basis of a number printed on a hoarding that was never describing you. Run the four numbers. Then choose whatever you like, knowing what it costs.
Frequently Asked Questions#
Why is the average package a poor guide?#
Because it is inflated by a small number of exceptional offers, it is expressed as cost to company rather than take-home pay, and it says nothing about what the programme cost you. The median for your intended function is far more informative.
What should I include in total cost?#
Programme fee for the full duration, accommodation and living expenses, travel and incidentals, and the salary you forgo while studying. For most candidates the forgone salary is the largest single component.
How do I compute payback period?#
Work out your annual increase in take-home earnings after the MBA compared with what you were earning before, then divide your total cost by that increase. The result is the number of years until the programme has paid for itself.
What is a reasonable loan repayment as a share of take-home pay?#
There is no universal figure, but the test is practical rather than numerical: if the repayment means you must take the highest-paying job available for several years regardless of interest, the loan is constraining the very options the MBA was meant to open.
Does this mean I should always choose the cheapest option?#
No. It means you should compare on payback rather than on reputation, and then choose within whatever range the arithmetic permits. Sometimes a more expensive programme genuinely pays back quickly because the outcome difference is large. Often it does not.
Should I count the network as part of the return?#
Qualitatively, yes. It is real value and it does not appear in the calculation. The framework is not an argument against paying for a strong network, only against doing so without knowing what it costs and how long it takes to recover.
What if I have no job to forgo?#
Then your forgone salary component is small, which improves the arithmetic considerably. Candidates entering directly from undergraduate study face a genuinely different calculation from experienced professionals, which is one reason two-year and one-year programmes suit different people.
Where do I get the median figures to run this?#
From each school's own published placement report, which is the primary source. Ask directly for the median by function and, where available, by prior background. A school that publishes only averages and highest packages has made a choice about what to disclose.